


Successful Cases

Fair Compensation for a Pickup Truck Injury
Despite a complex liability dispute, I secured the maximum policy limits for a client who suffered a traumatic injury after being thrown from the back of a pickup truck.
Fair Compensation for a Pickup Truck Injury
Despite a complex liability dispute, I secured the maximum policy limits for a client who suffered a traumatic injury after being thrown from the back of a pickup truck.
Car Accident Coverage Saved from False Cancellation
I won against an insurance company that tried to wrongfully deny coverage by falsifying documents, getting my client's policy reinstated and her claim paid in full.
Car Accident Coverage Saved from False Cancellation
I won against an insurance company that tried to wrongfully deny coverage by falsifying documents, getting my client's policy reinstated and her claim paid in full.
Rejected Car Accident Claim Wins Full Settlement
I overturned a liability denial on a case other lawyers rejected, securing the full policy limits for a client severely injured in a major collision.
Rejected Car Accident Claim Wins Full Settlement
I overturned a liability denial on a case other lawyers rejected, securing the full policy limits for a client severely injured in a major collision.

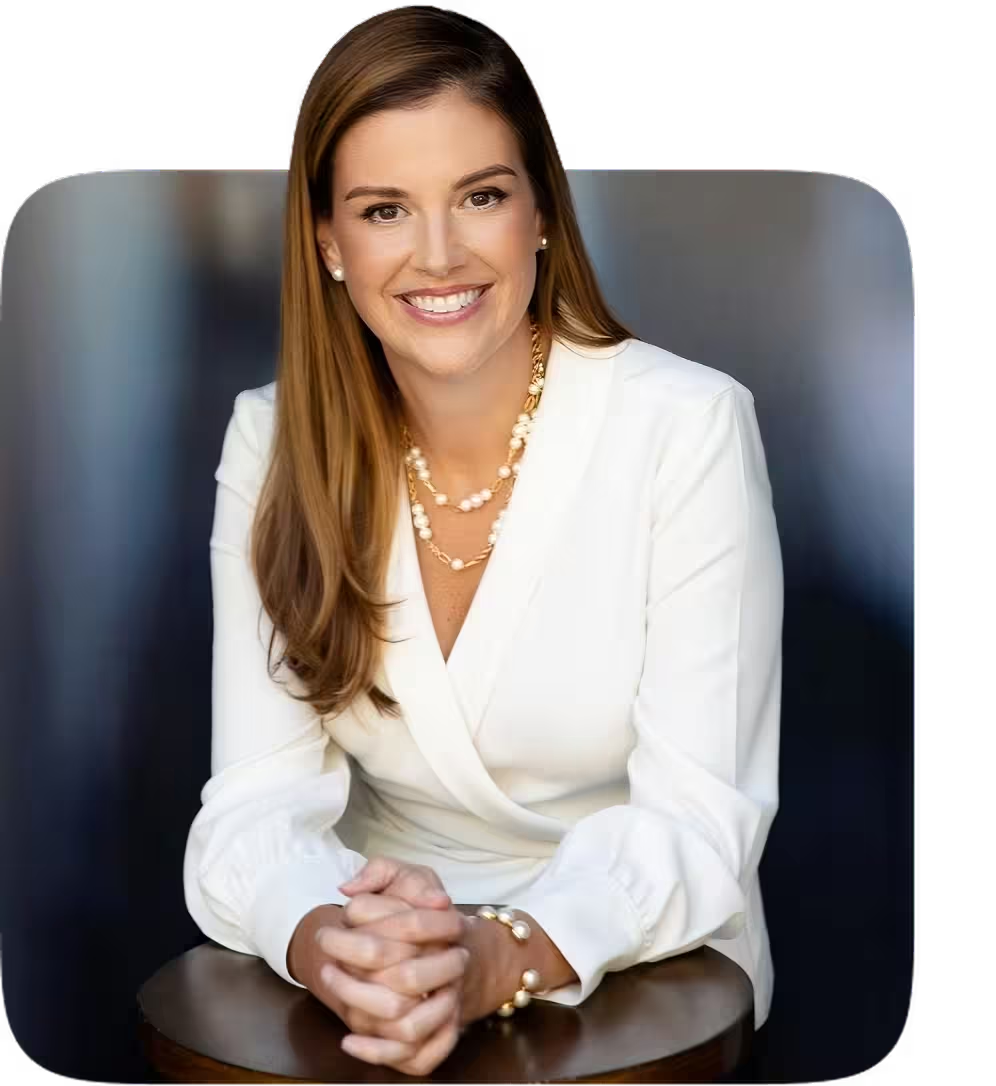
Applewhite
A Kyle Car Accident Lawyer Who Takes On the Insurer Personally
Three days. That's often how quickly the adjuster calls after a wreck at the Kyle Parkway and RM 1626 intersection, usually before the tow yard has even released your car. Whatever you say on that call, however casual it feels, tends to become the foundation the insurance company builds its entire payout around.
I'm Ashley Applewhite. Before I represented injured clients, I spent years on the defense side, handling claims for major insurance carriers. I sat in on the calls where a company decided how low it could go and still call the file closed. That view from the other side is exactly what I use now for the people those carriers try to underpay.
Your claim doesn't move to a case manager once the paperwork is filed. I'm the one reading the crash report, the one on the phone with the adjuster, and the one in front of a Hays County judge if the insurer forces it that far.
Car Accident Types in Kyle
Most of the crash claims I take on around Kyle start with a driver doing something ordinary and careless. On local roads, that tends to look like:
- Rear-end collisions where I-35 traffic near the Kyle/Buda split backs up faster than drivers react;
- Left-turn crashes at the busier intersections along FM 1626 and Kohlers Crossing;
- A driver checking a phone instead of the road through the retail corridor near Kyle Marketplace;
- Speeding on stretches of FM 150 that see less patrol coverage;
- Failure-to-yield wrecks where feeder roads dump into the interstate without enough gap;
- Pileups during the school drop-off and pickup rush near Jack C. Hays High School;
- Cars losing control when a sudden rainstorm hits the highway during evening traffic.
A car offers more protection than a bike or a bumper does against a truck, but that doesn't make these wrecks minor: it just means the damage sometimes hides better at first.
Dealing With an Insurance Adjuster After a Kyle Car Accident?
Let me take that conversation over. Reach out for a free consultation before you sign anything or give a recorded statement.
What a Kyle Car Accident Does to a Driver
No two collisions leave identical injuries, but a handful come up again and again in the cases I handle out of Kyle:
- Whiplash and soft-tissue strain that gets worse over the days after the crash, not better;
- Herniated or bulging discs from the jolt of a rear-impact hit;
- Broken bones that need plates, screws, or more than one surgery to set right;
- Concussions and traumatic brain injuries that don't always show up on the scene;
- Shoulder, knee, and joint damage from bracing against the wheel or dashboard;
- Burn injuries from airbag deployment, hot surfaces, or a post-collision fire;
- Internal injuries that stay quiet at first and turn serious hours or days later.
Some of these don't announce themselves until well after the tow truck leaves. I tell every client to get checked out the same day, even if nothing feels broken. A gap between the crash and your first doctor's visit is the first thing an adjuster reaches for when they want to argue you weren't really hurt.

Get a Second Opinion Before You Sign
An early settlement offer is rarely the last word on what your case is worth. Ask me before you agree to one.
Why Kyle Drivers Choose Applewhite Firm PLLC
How I run a car accident case is simple to describe and harder to actually deliver: lock in the proof early, put a real number on what the wreck cost you, and hold the insurer to it. Here's what that looks like for you as my client:

An Insider's Read on How Claims Get Priced
I spent years deciding, from the inside, how little an insurance company could offer and still close a file. That experience means I recognize a lowball number the moment it arrives and know exactly what evidence forces the company to raise it.

No Recovery, No Fee
Every car accident case runs on contingency. I front the costs of building it — records requests, filing fees, and any outside consultant the claim calls for — and I'm paid only out of what we recover. A case that doesn't pay off costs you nothing.

Nights, Weekends, Holidays — Still On
A collision doesn't wait until Monday morning, so I don't limit myself to business hours either. Text or call after 9 p.m. or on a Sunday and expect to hear back from me, not from a queue.

You Call Me, Not a Rotating Staff
There's no front-desk screener between you and your file. Questions about a letter you received, a doctor's note, or where things stand go straight to the attorney who's actually working your case.
The Path a Kyle Car Accident Claim Takes
You Tell Me What Happened
A short phone call gets this started. Once I hear the facts, I'll tell you plainly whether the claim is worth pursuing and flag anything that could complicate it, including if the answer is no. There's no charge for that first call.
I Work While You Heal
Your only job during this stretch is getting better. Behind the scenes, I'm requesting the vehicle inspection before it's released to salvage, pulling any nearby camera footage before it's overwritten, cleaning up mistakes in the police report, and fielding the adjuster's calls so you don't have to.
The Claim Gets Valued
I hold off on sending a demand until your medical picture has settled; sending one too early is how people leave money on the table. When the time is right, every dollar the crash cost gets tallied: treatment so far, care you'll still need, missed income, and how the injury has changed your routine, each one backed by paperwork.
I Push Past the First Offer
Insurers rarely open with a fair number. I counter it with the documentation we've built, keep negotiating, and take the case to court if the company refuses to move. Years of doing this from the inside means most adjusters know better than to expect me to fold.
Ready to Find Out Where You Stand?
Send me the details of your Kyle accident, and I'll go through them myself so you know what your case is worth and what the next move looks like.
FAQs About Car Accidents from Kyle Drivers
An adjuster already called with a settlement number. Should I take it?
Not without a second look. Fast offers usually mean the insurer wants to close the file before the full extent of your injuries is clear, and signing typically ends your right to ask for more later. Have me compare the number to your medical records first.
The other driver wasn't carrying enough insurance. What happens now?
You may still have a path to recovery. Uninsured or underinsured motorist coverage on your own policy can fill the gap when the at-fault driver's limits fall short or they had no coverage at all. I check every policy that could apply before assuming there's nothing to recover.
Am I required to give a recorded statement to the other driver's insurance company?
No, and it's rarely in your interest to give one. These statements are built around questions meant to get you downplaying your injuries or accepting blame. Send that call to me instead.
The insurance company says I share some of the blame. Is my case over?
Only if they can pin more than half the fault on you. Texas allows recovery at 50% fault or less, with your compensation reduced by that share. I build the record to push back when an insurer leans on this to cut what they owe.
What's the deadline for filing a car accident claim in Kyle?
Two years from the crash date, under Texas Civil Practice and Remedies Code § 16.003, for most cases. Claims against a government entity — a poorly maintained road, for example — carry a much shorter notice window.
